Table of Contents
- Why Real Tick Data Matters for MT5 Backtesting
- Importing Tick Data to MT5
- Understanding MT5 Backtest Modeling Quality
- Configuring Strategy Tester for Accurate Results
- MT5 Strategy Tester Optimization Best Practices
- Reading Backtest Reports and Performance Metrics
- Common Backtesting Pitfalls and How to Avoid Them
- Debugging Backtest Failures
- Frequently Asked Questions
Last Updated: September 23, 2026
Why Real Tick Data Matters for MT5 Backtesting
When you backtest MT5 robots real tick data, you’re testing against actual market movement. Real tick data captures every price movement that occurred during your test period, while generated ticks fill gaps without reflecting what actually happened.
Most traders discover this too late: they backtest with synthetic data, see great results, deploy live, and watch the strategy fail. When you backtest MT5 robots with real tick data, you’re working with the same market conditions your live trades will face. A strategy that looks profitable on synthetic data might hemorrhage money in real markets; real tick data eliminates this risk.
Importing Tick Data to MT5
Importing tick data into MT5 requires downloading history first, then placing files in the correct folder. Start by opening Market Watch, right-clicking your symbol, and selecting “Show in Market Watch.” Then open the terminal window and click the “Tester” tab to access the Strategy Tester interface.
MT5 stores tick data in a specific folder structure: navigate to the MT5 data folder, find the Ticks subfolder for your broker, place downloaded tick files there, and restart MT5. The folder location matters, if MT5 can’t find the files, it won’t load them.
Once files are in the correct location, open the Strategy Tester again. Select your symbol and timeframe. MT5 will scan for available history. If your tick files are present and properly formatted, they’ll appear in the available data list.
Download tick data from your broker’s history center when possible. Broker data matches your actual trading environment perfectly, eliminating data-source mismatches that can skew backtest results.
The import process completes automatically once you start a backtest. MT5 loads the tick data into memory and begins simulation. If the data loads successfully, your backtest will run. If not, check the logs for error messages.
Understanding MT5 Backtest Modeling Quality
MT5 backtest modeling quality determines how accurately your backtest simulates real trading. MT5 offers three modeling quality levels, each affecting how precisely the platform processes price data during simulation.
Every Tick vs. Every Tick Based on Real Ticks
Every Tick generates synthetic price movements between recorded ticks, faster but less accurate, as it assumes price movement follows a pattern that often breaks during fast markets or gaps. Every Tick Based on Real Ticks uses only actual market ticks with no synthetic data or assumptions, slower but far more reliable. For serious backtest accuracy, this is the only choice.
The performance difference can be striking: a strategy backtested with Every Tick might show 40% returns, while the same strategy with Every Tick Based on Real Ticks might show 25%, the second number is closer to reality.
Testing with Every Tick instead of Every Tick Based on Real Ticks can lead to severe overoptimization. Your backtest results will look better than live performance, sometimes dramatically so. This is one of the most common backtesting mistakes.
When you backtest MT5 robots with real tick data, use Every Tick Based on Real Ticks as your modeling quality; anything less introduces synthetic distortion that undermines your entire backtest.
Configuring Strategy Tester for Accurate Results
Proper configuration in the Strategy Tester prevents common errors that inflate backtest results. Several settings directly impact accuracy.
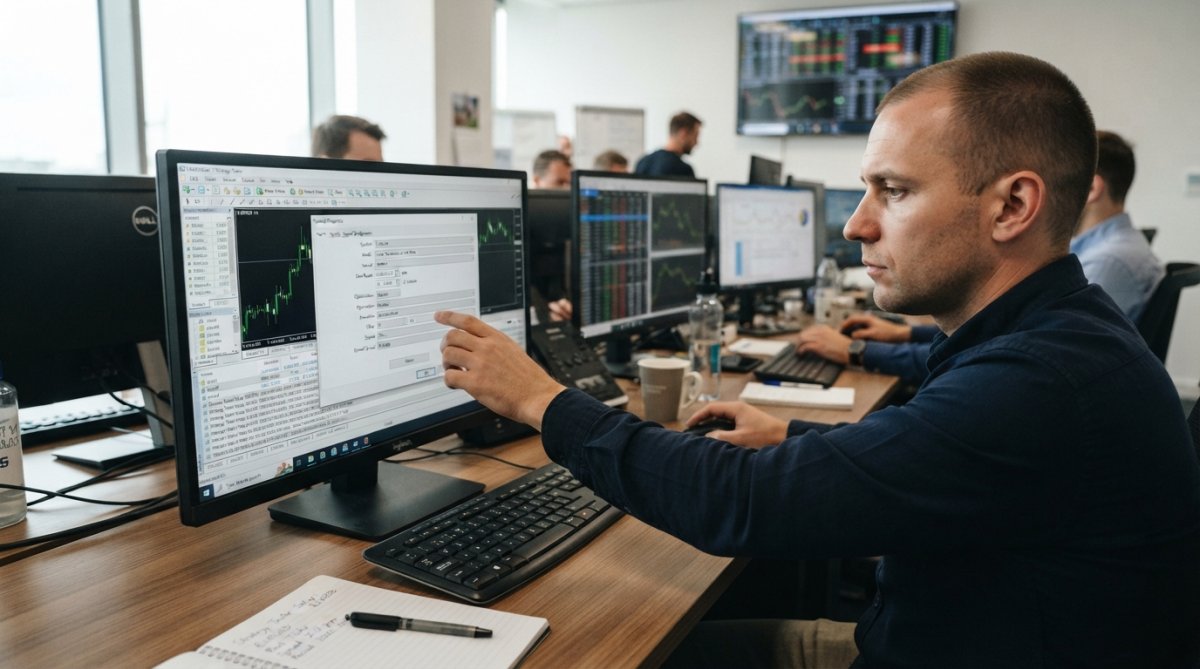
Open the Strategy Tester window in MT5. You’ll see several configuration options. The most critical are symbol, timeframe, modeling quality, and date range.
Select your symbol carefully. Make sure it matches your broker’s symbol name exactly. Mismatched symbols cause import errors and failed backtests.
Set your timeframe to match your strategy. If your strategy uses 1-hour bars, select H1. If it uses daily bars, select D1. Mismatched timeframes produce unreliable results.
Under “Modeling Quality,” select “Every Tick (based on real ticks)” if available. This ensures you’re using real tick data, not generated ticks.
Set your test period carefully. Start with a reasonable historical window, at least one year of data. More data is better, but ensure your data quality is consistent throughout the period.
Symbol Properties and Spread Settings
Open symbol properties and configure: spread (match your broker’s typical spread), slippage (set realistically, most traders experience 1-3 pips), commissions (enter exact amounts if applicable), and point size/digits (ensure correct interpretation of price data).
History Synchronization and Data Gaps
Data gaps cause backtest failures. Before you run a backtest, verify your data is complete and synchronized.
Open the Data Center in MT5. Select your symbol. Check the available history. If there are gaps, your backtest will be unreliable for those periods.
Many traders don’t notice data gaps until their backtest produces odd results. A gap might mean you’re testing with incomplete data for a critical market period.
Synchronize your data by downloading fresh history from your broker. MT5 has a built-in sync feature. Use it before important backtests.
Data gaps are silent killers of backtest accuracy. A gap of just a few days can make your results unreliable for an entire month of trading. Always verify data completeness before running a backtest.
MT5 Strategy Tester Optimization Best Practices
Optimization is where most backtesting efforts fail. A strategy that looks profitable on historical data often collapses in live trading because parameters were tuned too tightly to past conditions. Understanding the difference between robust optimization and overfitting is the difference between a strategy that works and one that merely looks good on a chart.
The Optimization vs. Backtesting Distinction
Backtesting validates a fixed strategy against historical data; optimization searches through thousands of parameter combinations to find the best performer. This search introduces a hidden danger: the more combinations tested, the higher the probability of finding one that worked by pure chance. This is the multiple comparisons problem, test 1,000 combinations and even a random strategy will show a few that appear profitable by statistical luck.
Detecting and Preventing Overfitting
The most reliable defense against overfitting is out-of-sample testing: divide your data into an optimization period (60-70%) and a validation period (30-40%). Optimize only on the first period, then test those parameters on the second period without re-optimizing. If performance degrades significantly on the validation period, you’ve overfit. Another detection method is parameter sensitivity analysis: if profit drops 50% when you change your stop loss by 5 pips, your strategy is fragile and likely overfit. Robust strategies tolerate small parameter variations.
Conservative Optimization Practices
Limit optimization to 2-3 core parameters (typically stop loss, take profit, or position sizing) with realistic step sizes, use 5 or 10 pip increments, not 0.1 pip. Use a minimum of 3-5 years of historical data; shorter periods are more prone to curve fitting. Consider walk-forward optimization: divide data into rolling windows, optimize on the first, test on the next, then move forward and repeat. This tests whether parameters remain effective as market conditions evolve.
The Risk-Return Trade-off in Optimization
Optimization always improves backtest results, that’s mathematically guaranteed. The question is whether the improvement reflects genuine edge or statistical noise. A strategy that shows 25% annual returns with conservative parameters might show 35% returns after optimization. But if that 35% is driven by overfitting, live trading will disappoint.
Accept that your optimized backtest results will be better than your live results.
Reading Backtest Reports and Performance Metrics
Your backtest report contains critical information about your strategy’s performance. Understanding these metrics prevents misinterpretation.
Equity Curve, Drawdown, and Profit Factor
The equity curve shows your account balance over time. A smooth upward curve is good. A jagged curve with big dips suggests high volatility or risk.
Common Backtesting Pitfalls and How to Avoid Them
Most backtesting failures trace back to a few repeating mistakes. Knowing these pitfalls helps you avoid them.
Overfitting and Curve Fitting Traps
Overfitting happens when your strategy becomes too tuned to historical data. The parameters work perfectly on the past but fail on the future.
Slippage, Latency, and Execution Model Gaps
Slippage is the difference between your expected entry price and your actual entry price. Backtests often assume zero slippage. Real trading has slippage.
Debugging Backtest Failures
When a backtest fails to run, the error message usually points to the problem. Common failures have common solutions.
Frequently Asked Questions
What is the difference between ‘every tick’ and ‘every tick based on real ticks’ in MT5?
Every Tick generates synthetic ticks from open, high, low, and close prices, which can miss price action between those points. Every Tick Based on Real Ticks uses actual historical tick data, creating a more accurate simulation of how your expert advisor would behave in live trading. Real tick backtesting reveals slippage and latency effects that synthetic models miss, making it essential for testing algorithmic trading robots.
How do I import custom tick data into MetaTrader 5?
Download tick history from a data provider in CSV or binary format compatible with MT5. Open the terminal, navigate to Tools > History Center, select your symbol, and import the file. Ensure the data format matches MT5 requirements: timestamp, open, high, low, close, and volume. After import, verify data synchronization by checking for gaps and comparing the tick count against the provider’s documentation.
Why is 100% modeling quality important when backtesting MT5 robots?
Modeling quality determines how closely your backtest simulates real market conditions. 100% modeling quality means the strategy tester is using complete tick-by-tick data, capturing every price movement and execution opportunity. Lower modeling quality uses interpolated or incomplete data, leading to overly optimistic results that fail in live trading. High-quality backtests with real tick data expose slippage, latency, and execution gaps before you risk real capital.
How can I tell if my backtest results are reliable or just curve fitting?
Test your expert advisor across different market conditions: bull markets, bear markets, and sideways ranges. Check if optimization parameters are stable across time periods. Use out-of-sample testing by optimizing on one date range and validating on another. Review the equity curve for smooth growth rather than sudden spikes. If results are too perfect (100%+ returns, zero losing trades), curve fitting is likely. Real trading robots show consistent but modest gains with occasional drawdowns.
Backtesting is how you separate strategies that work from strategies that only look good. When you backtest MT5 robots with real tick data, you gain confidence that your results reflect real market conditions. EZMT5 provides the tools and systems you need to test properly and trade with precision. Start with accurate backtesting, and your live trading results will follow.